Energy Storage System Market: Risks, Regions, and Technologies
What growth is real, and what is hype
- What technologies are counted inside today’s ESS market?
- Which market size numbers are most credible today?
- What is driving storage growth beyond renewables?
- Which regions are scaling storage fastest in 2026?
- When does mechanical storage outperform lithium-ion systems?
- The COP29 (2024) Global Energy Storage and Grids Pledge sets a 1,500 GW global storage capacity target by 2030 across all storage forms, and the European Commission cites this target.
- The European Commission projects the European Union (EU) electricity system renewable share rising from 47% in 2024 to around 69% by 2030 and 80% by 2050.
- The European Commission’s Joint Research Centre reports Europe’s operational storage power is around 66 GW and planned projects might double this to 132 GW by 2035.
- The U.S. Environmental Protection Agency says battery energy storage systems (BESS) stabilize grids, but lithium battery fires at some installations have raised legitimate safety concerns among communities.
- Technology comparisons should look beyond upfront cost to lifetime cycling limits, degradation behavior, and safety test regimes, especially when evaluating emerging mechanical storage options.
- Introduction: How to Read the Market
- What Is the Energy Storage System Market?
- How Big Is the Energy Storage Market and How Fast Is It Growing?
- Key Growth Drivers in the Energy Storage Market
- Why Are People Against BESS? Market Constraints and Risks
- Regional Breakdown: Where Energy Storage Is Growing Fastest
- Lithium-Ion vs. Mechanical Storage: Comparing the Technologies
- Who Are the Leaders in the Energy Storage Market?
- Is 4-Hour Storage Still the Industry Standard?
- What Is the Outlook for the Energy Storage Systems Market?
- Conclusion: What Buyers Should Watch
Introduction: How to Read the Market
Buyers face a fast-moving energy storage system market where outcomes hinge on whether a system is bankable under real duty cycles, local permitting rules, and long operating horizons.
This guide frames the market through technology tradeoffs. It then connects those tradeoffs to regional buildout signals and to the risks that most often decide projects: safety, permitting, and lifetime performance.
What Is the Energy Storage System Market?
In practical terms, the energy storage system (ESS) market covers engineered solutions that can store energy and dispatch it later to support reliability, economics, or resilience. The U.S. Environmental Protection Agency writes that battery energy storage systems help stabilize electrical grids by providing steady power flow despite fluctuations from inconsistent renewable generation.
An energy storage system market groups products and projects that store energy and later dispatch it, including battery energy storage systems, mechanical storage, and thermal storage, measured by power (MW) and energy (MWh) rather than by technology alone.
A useful way to scope the market is to separate systems by storage medium and by how they connect and operate, because that is what drives permitting, safety requirements, and revenue models.
- Battery energy storage systems (BESS): usually lithium-ion systems that shift electricity in time and provide grid services.
- Pumped storage hydropower: large, long-duration mechanical storage that is highly site-dependent.
- Compressed air storage: mechanical storage that depends on specific plant designs and suitable sites.
- Flywheel storage: mechanical storage designed for very fast response, with designs ranging from short to multi-hour use cases.
- Thermal storage: stores heat and can support power or industrial energy uses, depending on the system design.
- Hybrid systems: combine technologies to match complex duty cycles and reduce operational stress on any single component.
How Big Is the Energy Storage Market and How Fast Is It Growing?
Sizing the market starts with scope clarity: power in GW versus energy in GWh, and whether a report counts batteries only or all storage forms. The COP29 (2024) Global Energy Storage and Grids Pledge sets a 1,500 GW target for global storage capacity by 2030 across all storage forms — roughly a six-fold increase — and the European Commission cites this target. Separately, Market Research Future estimates the energy storage market could reach about USD 226 billion by 2035 at a CAGR near 21%, depending on how the market is defined.
| Metric | What it covers | Value | Publisher |
|---|---|---|---|
| Global storage capacity by 2030 | Total capacity across all storage forms | 1,500 GW (target) | COP29 pledge |
| Market size by 2035 | Global energy storage market (estimate) | USD 226B (≈21% CAGR) | Market Research Future |
These figures combine installed capacity and market value estimates, not a single comparable metric. Market estimates can differ by scope (batteries-only versus all storage) and by what is counted (equipment versus full system delivery).
Key Growth Drivers in the Energy Storage Market
Storage demand grows as grids add variable generation and need more dispatchable flexibility. The European Commission projects the renewable share in the European Union (EU) electricity system rising from 47% in 2024 to around 69% by 2030 and 80% by 2050, which increases the need for time-shifting and balancing.
These forces compound demand for dispatchable flexibility and reshape what storage buyers prioritize.
Renewables
More wind and solar increase daily balancing needs.
Electrification
EVs and heat pumps raise peaks and volatility.
AI Data Centers
Fast load swings stress batteries and grid assets.
Policy Incentives
Mandates and tariffs shift project economics and timing.
Grid Congestion
Interconnection delays increase the value of local flexibility.
One practical example is solar-plus-storage: it shifts midday solar output into evening demand peaks, when prices and grid stress rise. That operating pattern is one reason four-hour storage has become a common default duration in many procurement templates.
As these drivers stack, buyers pay closer attention to lifetime cycling and performance stability, because those determine whether an asset can earn across many years of market conditions.
Why Are People Against BESS? Market Constraints and Risks
Pushback against battery projects is usually about project risk, not about whether storage is needed. The U.S. Environmental Protection Agency notes that while BESS technology is designed to bolster grid reliability, lithium battery fires at some installations have raised legitimate safety concerns in many communities. At the same time, demand is booming while margins are pressured along the battery value chain as LFP cells commoditize and price competition intensifies.
- Safety concerns: fire risk perception can change siting and local acceptance.
- Permitting uncertainty: timelines and conditions can shift project economics.
- Insurance and liability: risk allocation can raise all-in costs.
- Warranty operating limits: contracts can constrain cycling strategies.
- Commodity pricing pressure: commoditized LFP cells and price competition can squeeze margins.
- Revenue volatility: spreads and market rules can change quickly and unevenly.
For buyers, the practical response is to specify operating assumptions clearly and align them with safety design, warranty terms, and community engagement from the start.
Regional Breakdown: Where Energy Storage Is Growing Fastest
Regional growth depends on grid needs, permitting pathways, and pipeline maturity. In Europe, the European Commission’s Joint Research Centre reports Europe’s current total operational storage power is around 66 GW, and planned projects mean this might double to 132 GW by 2035.
Globally, storage is increasingly treated as core infrastructure in planning and regulation, which raises the bar on bankability, safety evidence, and supply chain resilience.
- Europe: pipeline growth is visible in the 66 GW to 132 GW trajectory.
- United States: Virginia SB 448 (April 2026) sets a 4.5 GW long-duration storage (10+ hours) target by 2045 for Dominion Energy and Appalachian Power; the law defines long-duration as 10 hours or more at full rated output. The Section 301 tariff on Chinese non-EV lithium-ion batteries rose from 7.5% to 25% on January 1, 2026; other duties can stack on top, so importers should confirm the current total rate.
- Asia Pacific: buildout is tied to supply chains; China dominates lithium-ion manufacturing.
- Middle East: projects track high-solar build programs.
- What to verify: interconnection queues, fire codes, and market rules vary by region.
Lithium-Ion vs. Mechanical Storage: Comparing the Technologies
Technology choice is increasingly about lifetime outcomes, not only upfront cost. IEEE Smart Grid summarizes results of safety-related abuse tests described in the UL 2580 and IEC 62660-2 standards. For stationary ESS procurement, buyers commonly look for UL 9540 system listing and UL 9540A fire-test results, and reference NFPA 855 for installation and fire-code alignment.
Mechanical storage covers several very different technologies, but the common theme is shifting risk away from electrochemistry. The tradeoff is that performance and bankability evidence can vary widely by technology type and maturity.
Lithium-Ion BESS
- Mature supply chain for standardized projects
- High round-trip efficiency in many applications
- Degradation can reduce usable capacity over time
- Fire safety requires mitigation and siting
- Warranty terms can limit cycling strategies
- Recycling and end-of-life planning required
Mechanical Storage
- Long asset horizons in some designs
- Non-flammable medium can ease safety concerns
- Geography constraints for pumped hydro and compressed air energy storage (CAES)
- Performance depends on specific technology maturity
- Can target frequent cycling without capacity fade
- Bankability hinges on validation and pilots
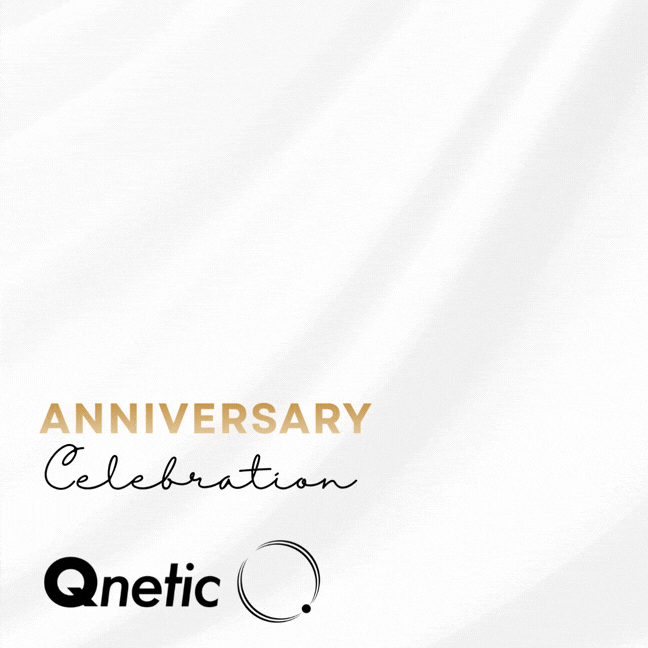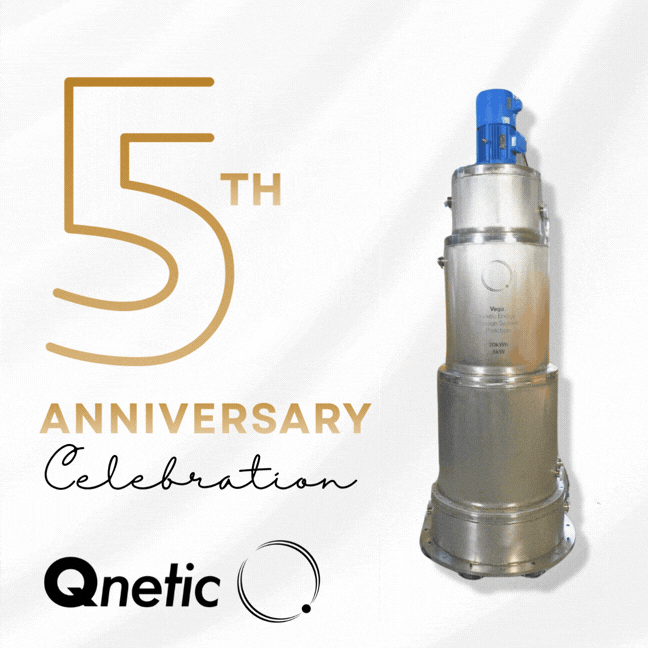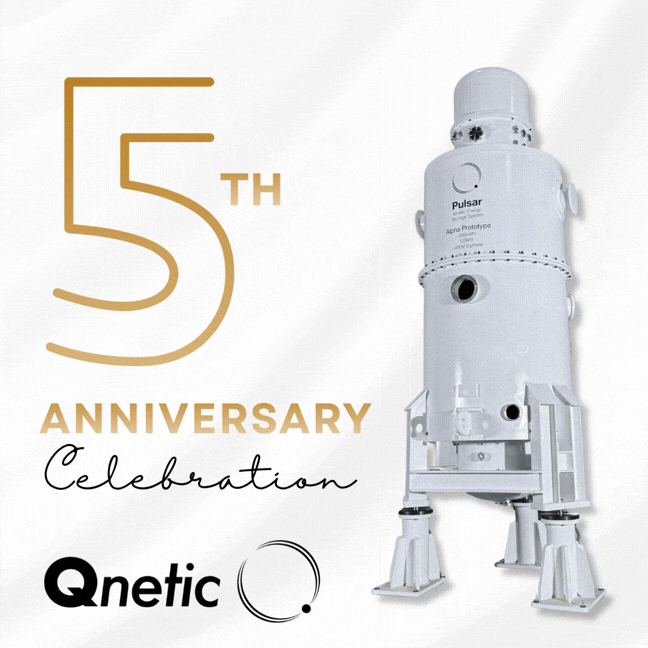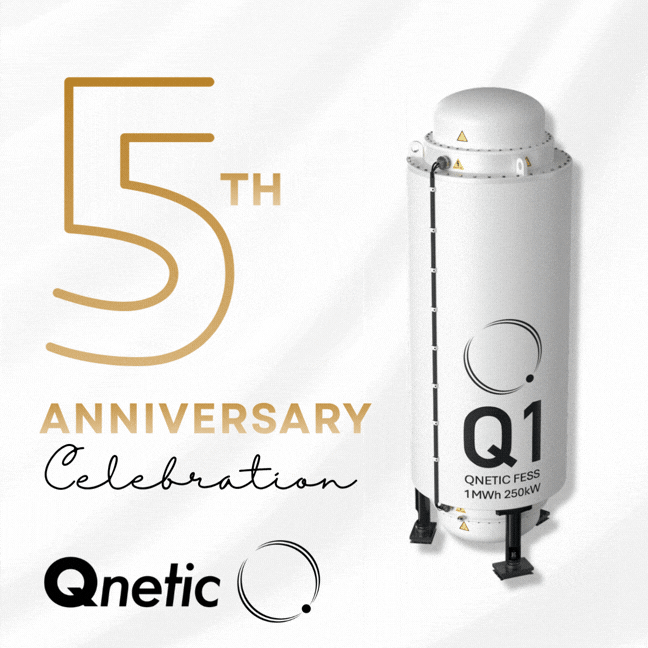
One mechanical path under development is Qnetic’s flywheel-based design, which Qnetic describes as a kinetic or mechanical battery. Qnetic states a round-trip efficiency range of roughly 80 to 88% and an idle holding time of more than 15 days as design targets.
Who Are the Leaders in the Energy Storage Market?
Leadership depends on what you measure: deployment volume, financing acceptance, or technology depth. In commodity battery markets, leaders are often the organizations that can deliver repeatable projects at scale; in long-duration segments, leaders are those with proven assets and permitting experience. In this context, EPC contractors are engineering, procurement and construction firms that deliver grid-connected projects end to end.
| Leader type | What they tend to lead on | What buyers should verify | Examples mentioned here |
|---|---|---|---|
| Utility-scale BESS vendors | Standardized delivery and integration packages | Safety approach, warranty terms, integration scope | Tesla (Megapack), BYD, Sungrow, Fluence; CATL (cells) |
| System integrators and EPCs | Permitting, interconnection, commissioning execution | Schedule risk allocation, performance guarantees | Grid-connected storage projects |
| Long-duration developers | Multi-hour to multi-day energy shifting assets | Siting feasibility, timelines, financing structure | Pumped storage and compressed air |
| Mechanical storage innovators | Alternative lifetime and safety profiles | Independent validation, duty-cycle evidence | Flywheel developers; Qnetic (first deliveries planned from 2028) |
In practice, a “leader” usually means deployment scale and repeatable execution. Buyers should still require documented performance under their duty cycle and under the safety and permitting rules in their region.
Is 4-Hour Storage Still the Industry Standard?
Four-hour duration remains common because it matches many peak-shaving and arbitrage windows and fits standardized system designs. It is also reinforced by California resource adequacy rules, where storage typically receives full qualifying capacity credit when it can sustain its maximum discharge for four hours. In CPUC terms, storage qualifying capacity is the maximum continuous output a resource can deliver over a four-hour window. From 2025, the Slice-of-Day framework shifts toward hourly showings rather than a single duration check. At the same time, long-duration mandates like Virginia SB 448 (April 2026) set a 4.5 GW long-duration storage (10+ hours) target by 2045 for Dominion Energy and Appalachian Power, with long-duration defined as 10 hours or more at full rated output.
- Why four hours: it fits many market products and dispatch windows.
- What it solves: daily shifting and common capacity needs.
- Where it breaks: longer ramps and extended stress events.
- How buyers specify: duration plus availability and cycling assumptions.
- Why hybrids grow: they match mixed fast and long needs.
The right duration is a function of duty cycle and market design, not a universal standard. Buyers should model the dispatch profile they will actually run, then match technology to that profile.
What Is the Outlook for the Energy Storage Systems Market?
The direction is clear: more capacity, higher scrutiny on safety, and wider technology diversity. Modeling by McKinsey for the Long Duration Energy Storage Council uses a 2021 baseline: global need at 1.5 to 2.5 TW of long-duration storage by 2040 — roughly 8 to 15 times the storage capacity installed in 2021. As of 2025, pumped storage exceeds 200 GW (IHA), and the IEA reports battery storage in 2025 at eleven times its 2021 level.
- Capacity scale: long-duration needs rise into the terawatt range by 2040.
- Renewables integration: higher variable shares increase shifting value.
- Safety scrutiny: community acceptance depends on credible risk controls.
- Standards and testing: abuse testing regimes shape procurement expectations.
- Technology mix: long-duration options gain attention where needed.
For decision-makers, the outlook translates into clearer procurement requirements: documented evidence, transparent assumptions, and lifetime economics aligned to the revenue model.
Conclusion: What Buyers Should Watch
Buying decisions increasingly hinge on experience and trust, not only on modeled economics. For newer storage approaches, the key question is whether validation is independent, standards-based, and tied to real utility decision pathways.
EPRI Independent Technology Assessment (Sponsored By SMUD)
- INITIAL SITUATION
- Utilities need independent, standards-based validation before committing multi-decade budgets to a new storage technology. Data sheets alone rarely answer questions about safety, control behavior, and performance under real grid duty cycles.
- APPROACH
- Qnetic entered EPRI’s independent technology assessment program, sponsored by SMUD. EPRI is assessing the technology for eight leading utilities and developers representing more than 40,000 MW of future demand, alongside two planned 2027 pilots.
- STATUS
- Results are scheduled, not yet measured. SMUD beta units are targeted for early 2027, and AI-grade duty-cycle testing with Arevon is planned from mid-2027 at the National Lab of the Rockies.
Brand solution efforts often target two buyer pain points in lithium-ion deployments: degradation-driven economics and fire-risk perceptions. For example, Qnetic is developing the Q500 with targets of 500 kWh, 125 kW, roughly 80 to 88% round-trip efficiency, and a 30-year design life; these are stated as targets rather than measured results.
A market view is only useful if it changes how you buy. Start with your duty cycle and constraints, then shortlist technologies whose lifetime economics and safety posture match the job, not just the lowest day-one bid.
In practice, that means tracking three signals: capacity buildout (how fast regions scale), renewables penetration (what drives shifting demand), and bankability proof (standards, pilots, and operational evidence).
FAQ
What technologies are counted inside today’s ESS market?
Most definitions include battery energy storage systems, pumped storage hydropower, compressed air, flywheels, and thermal storage. The exact scope depends on whether a report counts only electricity storage or also heat-to-power systems.
Which market size numbers are most credible today?
Start with the scope and unit: power in GW versus energy in GWh. A widely cited benchmark is the COP29 Global Energy Storage and Grids Pledge target of 1,500 GW by 2030, across all storage forms.
Why are people against BESS?
Concerns are often local and practical: siting, emergency response, and perceived fire risk. The U.S. Environmental Protection Agency notes lithium battery fires at some installations have raised legitimate safety concerns in many communities.
Which regions are scaling storage fastest in 2026?
Growth depends on policy and grid needs. In Europe, the Joint Research Centre reports around 66 GW operational storage power, with planned projects that might double it to 132 GW by 2035.
When does mechanical storage outperform lithium-ion systems?
Mechanical storage can win when long asset life, non-flammable operation, or frequent cycling matters more than peak efficiency. Examples include pumped hydro, compressed air, and emerging flywheel designs targeting multi-hour discharge.
What standards guide lithium-ion safety testing for energy storage?
IEEE Smart Grid notes abuse testing described in UL 2580 and IEC 62660-2. For stationary procurement, buyers typically ask for UL 9540 system listing and UL 9540A test results (and often UL 1973, IEC 62619, and NFPA 855 alignment).
Does 1,500 GW by 2030 refer only to batteries?
No. The COP29 pledge target is framed as global storage capacity across all storage forms by 2030. Any market report should be checked for whether it uses the same broad scope.